MARKET RESEARCH REPORT
Hand Polished Optical Lenses Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
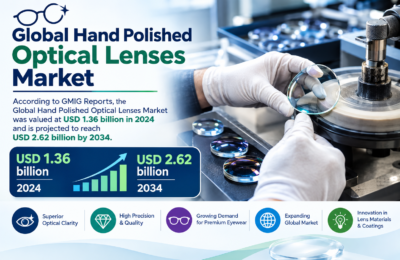
The global hand polished optical lenses market has maintained steady, specialized demand, anchored in applications where surface quality, wavefront precision, and defect-free finishing exceed what fully automated computer-controlled polishing processes can reliably achieve at required tolerances. According to GMI Reports, the market was valued at USD 1.36 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 6.8%, reaching USD 2.62 billion by 2034.
Growth is being reinforced by sustained demand from defense, aerospace, and scientific research applications requiring ultra-high-precision optics beyond standard commercial tolerances, continued growth in advanced laser system and photonics research requiring custom, small-batch lens finishing, and persistent niche demand within high-end telescope, microscopy, and specialized medical device optics where hand-finishing techniques remain the preferred approach for achieving specific optical performance characteristics.
Hand polishing continues to occupy a specialized niche within the broader precision optics manufacturing industry, valued specifically for its ability to achieve exceptionally low surface roughness, correct complex aspheric and freeform surface errors identified during interferometric testing, and produce small-batch or prototype optical components where the capital investment in automated computer-controlled polishing equipment cannot be economically justified. Skilled optical technicians remain essential to this specialized manufacturing segment despite broader industry automation trends.
Market Overview
The global hand polished optical lenses market encompasses precision optical components finished through manual or semi-manual polishing techniques performed by skilled optical technicians, typically used where surface quality requirements, complex geometries, or low production volumes make automated computer-controlled polishing processes economically or technically impractical. Core applications include defense and aerospace optical systems, scientific research instrumentation, high-end telescope optics, specialized medical device components, and prototype or small-batch precision optics production.
Hand polishing techniques remain particularly valued for correcting complex aspheric and freeform optical surface errors identified through interferometric testing, a capability that requires the tactile skill and iterative judgment of experienced optical technicians rather than purely programmatic automated processes. The segment also serves critical prototyping and low-volume production needs where the substantial capital investment required for automated computer-controlled polishing equipment cannot be justified by production volume.
The competitive landscape features a mix of specialized precision optics manufacturers with dedicated hand-finishing capabilities and departments within larger optical component companies maintaining hand-polishing expertise alongside primarily automated production lines. Defense and aerospace procurement, along with scientific research institution demand, represents the most stable and consistent revenue base for manufacturers specializing in this labor-intensive manufacturing approach.
Market Size & Forecast
Market Driving Factors
1. Sustained Defense and Aerospace Precision Optics Demand
Continued defense and aerospace sector demand for ultra-high-precision optical components used in targeting systems, reconnaissance instruments, and guidance systems requires surface quality tolerances that frequently exceed the reliable capability of standard automated polishing processes, sustaining consistent demand for specialized hand-finishing expertise.
2. Growth in Advanced Laser and Photonics Research
Expanding research investment in advanced laser systems and photonics applications, including high-power laser research and quantum optics experimentation, continues to generate demand for custom, small-batch precision lens finishing that hand-polishing techniques are well-suited to economically fulfill given typically limited production volumes.
3. Complex Aspheric and Freeform Surface Correction Requirements
Growing use of complex aspheric and freeform optical surfaces across high-performance optical systems continues to require skilled hand-finishing capability for correcting surface errors identified through interferometric testing, a specialized correction process that remains difficult to fully automate given the iterative, judgment-based nature of the finishing process.
4. High-End Telescope and Astronomical Instrument Demand
Sustained demand from both professional astronomical research institutions and premium amateur telescope markets for exceptionally high-quality primary and secondary mirror optics continues to support specialized hand-finishing manufacturers serving this quality-sensitive, relatively low-volume application segment.
5. Prototype and Low-Volume Specialized Medical Device Optics
Growing development of specialized medical device optical components, including advanced endoscopic and surgical visualization systems, continues to generate prototype and low-volume production demand where hand-finishing techniques offer more economical and flexible production pathways than automated equipment investment.
Market Restraining Factors
1. Skilled Labor Scarcity and Workforce Aging
The specialized hand-polishing optical technician workforce continues to face scarcity and aging demographic challenges, as the extensive apprenticeship and skill development required for this craft has not attracted sufficient new entrants relative to retiring experienced technicians, creating capacity constraints across the industry.
2. Continued Advancement of Automated Computer-Controlled Polishing
Ongoing technological advancement in computer-controlled optical polishing and magnetorheological finishing equipment continues to expand the range of applications where automated processes can achieve comparable surface quality to hand-finishing techniques, gradually narrowing the addressable application scope for manual polishing methods.
3. High Per-Unit Production Costs and Extended Lead Times
Hand-polishing processes inherently require substantially longer production timelines and higher per-unit labor costs relative to automated alternatives, limiting the economic viability of hand-finishing techniques to specialized, high-value applications where quality and precision requirements justify the premium cost structure.
4. Production Volume and Scalability Limitations
The inherently labor-intensive nature of hand-polishing techniques imposes practical production volume and scalability limitations, restricting the market’s addressable application scope to specialized, low-volume, and high-value optical component production rather than mainstream commercial optics manufacturing.
Market Segmentation
By Lens Type
The hand polished optical lenses market is segmented by lens type into spherical lenses, aspheric lenses, and freeform/complex geometry lenses.
Aspheric lenses retain the largest and growing share given their prevalence in high-performance optical systems requiring surface error correction beyond automated process capability, while freeform and complex geometry lenses are gaining share fastest as advanced optical system designs increasingly incorporate non-traditional surface geometries.
By Material
The market is segmented by material into optical glass, fused silica/quartz, and specialty crystal materials.
By End-Use Application
Competitive Landscape
The global hand polished optical lenses market remains highly specialized and fragmented, featuring dedicated precision optics manufacturers with in-house hand-finishing expertise alongside specialized departments within larger optical component companies. The leading ten companies account for a modest combined share of total global market revenues, reflecting the segment’s specialized, craft-oriented competitive structure.
Regional Analysis
North America leads the global hand polished optical lenses market, generating an estimated 39% of total global revenues, supported by concentrated defense and aerospace procurement and a dense cluster of specialized precision optics manufacturers in the Rochester, New York region. Europe and Asia Pacific represent significant secondary markets, with Asia Pacific showing growing demand from expanding domestic defense and scientific research investment.
Emerging Market Trends
Hybrid Automated-Manual Finishing Workflows
Manufacturers are increasingly adopting hybrid workflows that combine automated computer-controlled roughing and initial polishing stages with final hand-finishing correction, optimizing production efficiency while retaining the precision benefits of skilled manual technique for final surface quality achievement.
Advanced Interferometric Testing Integration
Growing integration of increasingly sophisticated interferometric testing equipment directly within hand-polishing workflows is improving technician feedback loops and precision outcomes, enabling more efficient iterative correction of complex surface errors during the manual finishing process.
Structured Apprenticeship and Skills Development Programs
Recognizing persistent skilled workforce scarcity, leading manufacturers and industry associations are increasingly investing in structured apprenticeship and technical training programs aimed at developing new generations of skilled optical hand-finishing technicians to address long-term workforce sustainability concerns.
Expansion into Emerging Quantum and Photonics Applications
Growing quantum computing and advanced photonics research investment is creating new specialized demand for ultra-high-precision hand-finished optical components, representing an emerging application area expanding beyond the segment’s traditional defense, aerospace, and astronomical instrument customer base.
Key Companies in the Hand Polished Optical Lenses Market
-
Optimax Systems Inc.
-
JML Optical Industries Inc.
-
Rochester Precision Optics LLC
-
II-VI Incorporated (Coherent Corp.)
-
Edmund Optics Inc.
-
Precision Optical Corporation
-
Zygo Corporation (AMETEK)
-
LightPath Technologies Inc.
-
Carl Zeiss AG (Specialty Optics Division)
-
Sydor Optics Inc.
-
Other Regional and Specialized Optics Manufacturers
Report Target Audience
-
Precision Optics and Photonics Manufacturers
-
Defense and Aerospace Procurement Bodies
-
Investment and Private Equity Firms
-
Scientific Research Institutions and Laboratories
-
Medical Device Optics Manufacturers
-
Management Consulting and Advisory Firms
-
Astronomical Instrument and Telescope Manufacturers
-
Academic Researchers in Optical Engineering
Market Segmentation Summary
By Lens Type
-
Aspheric Lenses
-
Freeform/Complex Geometry Lenses
-
Spherical Lenses
By Material
-
Optical Glass
-
Fused Silica/Quartz
-
Specialty Crystal Materials
By End-Use Application
-
Defense & Aerospace
-
Scientific Research & Laser Systems
-
Astronomical Instruments & Telescopes
-
Medical Device Optics
By Region
-
North America
-
Europe
-
Asia Pacific
-
Middle East
-
Rest of World
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com