MARKET RESEARCH REPORT
Coconut Products Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
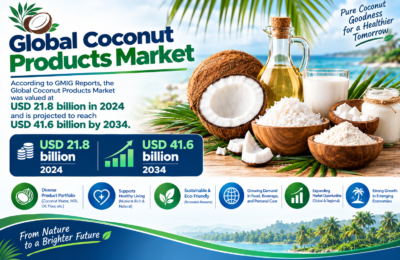
The global coconut products market was valued at USD 21.8 billion in 2024 and is projected to grow at a compound annual growth rate (CAGR) of approximately 6.7%, reaching USD 41.6 billion by 2034, according to GMI Reports. The coconut products market encompasses a remarkably diverse portfolio of products derived from the coconut palm (Cocos nucifera), including coconut water, coconut milk and cream, coconut oil, desiccated coconut, coconut flour, coconut sugar, coconut-based personal care and cosmetic ingredients, coir fiber products, and activated carbon from coconut shell, collectively serving food and beverage, personal care, pharmaceutical, industrial, and horticultural end-use sectors worldwide.
The market has experienced a remarkable resurgence over the past decade, propelled by the global wellness movement’s embrace of coconut water as a natural hydration beverage, the plant-based dairy alternative boom elevating coconut milk and cream demand, growing consumer preference for natural and organic personal care ingredients, and rising adoption of vegan and gluten-free dietary lifestyles that favor coconut-derived ingredients. This broad-based consumer trend alignment has transformed coconut from a primarily tropical regional commodity into a globally mainstream functional food and wellness ingredient.
Asia Pacific dominates global coconut production, with Indonesia, the Philippines, and India collectively accounting for approximately 70% of world coconut output, positioning these countries as primary supply sources for the global market. However, the market’s highest-value growth is occurring in North America and Europe, where premium consumer demand for coconut water, organic coconut oil, and coconut-based plant dairy alternatives drives substantial import volumes and branded product development investment from both established food and beverage companies and innovative emerging brands.
Market Overview
The global coconut products market encompasses primary agricultural production of coconuts across tropical coastal regions of Asia Pacific, Latin America, Africa, and Oceania; primary processing into copra, coconut oil, desiccated coconut, coconut milk, coconut water, and coir fiber; secondary value-added manufacturing producing branded consumer products including packaged coconut water, coconut milk beverages, coconut-based snacks, and personal care formulations; and industrial applications including coconut shell activated carbon and coir-based horticultural substrates.
Coconut oil represents the largest product category by market value, with applications spanning edible oil, specialty food ingredient, personal care and cosmetic formulation, and industrial oleochemical feedstock. The market encompasses both virgin coconut oil, commanding substantial premium pricing within the health and wellness food channel, and refined, bleached, and deodorized coconut oil serving mainstream food manufacturing and industrial oleochemical applications. Coconut water has emerged as the highest-growth beverage category, capturing consumer demand for natural electrolyte hydration alternatives to conventional sports drinks.
The coconut supply chain faces notable structural challenges including aging coconut palm plantations with declining productivity in major producing countries, vulnerability to climate change-driven weather events including typhoons and drought affecting yield, smallholder farmer income vulnerability within a predominantly smallholder-based production system, and limited investment in replanting and productivity improvement. These supply-side structural issues create price volatility and supply availability considerations that influence downstream market dynamics and are driving sustainability-focused supply chain investment programs.
Market Size & Forecast
Market Driving Factors
1. Global Wellness Movement and Natural Hydration Beverage Demand
The sustained global consumer wellness movement’s embrace of coconut water as a natural, low-calorie, electrolyte-rich hydration beverage alternative to sugary sports drinks and carbonated beverages has driven exceptional category growth, particularly across North America, Europe, and increasingly Asia Pacific middle-class consumer segments. Coconut water’s naturally occurring potassium, magnesium, and electrolyte content, combined with its clean label simplicity, aligns perfectly with consumer preference for minimally processed, naturally functional beverages.
2. Plant-Based Dairy Alternative Market Expansion
The rapid global expansion of the plant-based dairy alternative sector, driven by growing lactose intolerance awareness, vegan and flexitarian dietary adoption, and environmental sustainability consciousness, is generating substantial coconut milk, coconut cream, and coconut yogurt demand. Coconut-based dairy alternatives offer distinctive creamy texture and rich flavor profile advantages in ice cream, yogurt, cooking cream, and barista beverage applications where nut and oat-based alternatives face texture or flavor limitations.
3. Natural and Clean Beauty Personal Care Ingredient Demand
Growing consumer demand for natural, plant-derived, and sustainably sourced personal care and cosmetic ingredients is driving strong coconut oil, coconut-derived surfactant, and coconut fatty acid derivative demand across skin care, hair care, and cleansing product formulations. Coconut oil’s moisturizing and emollient properties, combined with coconut-derived surfactants’ mild cleansing characteristics and renewable plant origin, position coconut ingredients as preferred components within clean beauty formulation strategies.
4. Vegan, Gluten-Free, and Keto Dietary Trend Alignment
Coconut-derived products’ natural alignment with vegan, gluten-free, paleo, and ketogenic dietary approaches has created substantial demand from health-motivated consumers following these dietary frameworks. Coconut flour, coconut oil, and MCT oil derived from coconut are staple ingredients within low-carbohydrate and ketogenic dietary patterns, supporting sustained demand from this dedicated and brand-loyal consumer segment across both retail grocery and online direct-to-consumer purchase channels.
5. Industrial and Specialty Application Expansion
Growing industrial application demand for coconut-derived materials, including coconut shell activated carbon for water treatment, air purification, and gold recovery applications, coir fiber and coco peat for horticultural growing media and erosion control, and coconut-derived oleochemicals for biodegradable surfactant and lubricant production, is diversifying coconut product revenue streams beyond food and personal care applications. Sustainability-driven substitution of petroleum-derived alternatives with coconut-based renewable materials supports this industrial demand growth.
6. Premiumization and Organic Certification Value Growth
Increasing consumer willingness to pay premium prices for organic, fair trade certified, single-origin, and sustainably sourced coconut products is driving significant value growth within the coconut market independent of volume expansion. Premium virgin coconut oil, organic cold-pressed coconut water, and certified sustainable coconut sugar products command substantial price premiums that support producer income improvement and encourage investment in quality-focused processing and certification infrastructure.
Market Restraining Factors
1. Aging Coconut Palm Plantations and Supply Productivity Constraints
A significant proportion of coconut palm plantations across major producing countries including the Philippines, Indonesia, and India are aging beyond optimal productive lifespan, with palm productivity declining as trees exceed 60 years of age. Insufficient replanting investment, driven by the long gestation period of new palms before first harvest and smallholder farmers’ limited access to replanting finance, is constraining supply growth potential relative to rapidly expanding global demand.
2. Climate Change Vulnerability and Weather Event Disruption
Coconut production in major producing regions is increasingly exposed to climate change-intensified weather risks including typhoon destruction of palm plantations, prolonged drought reducing nut yield, and emerging pest and disease pressure including coconut rhinoceros beetle and cadang-cadang disease expansion. These climate-related supply disruption risks create supply availability uncertainty and price volatility that affect downstream manufacturers’ procurement planning and cost management.
3. Saturated Fat Health Perception Challenges for Coconut Oil
Coconut oil’s high saturated fat content has generated sustained public health debate, with authoritative health organizations including the American Heart Association advising caution regarding coconut oil consumption in the context of cardiovascular health. This health perception controversy has moderated coconut oil demand growth in health-conscious consumer segments relative to its earlier wellness superfood positioning peak, requiring brands to shift positioning toward culinary and cosmetic applications less dependent on health claims.
4. Smallholder Farmer Income Vulnerability and Supply Chain Fragmentation
The global coconut supply chain’s dependence on an estimated 10+ million smallholder farming households with average landholdings below two hectares creates structural supply chain fragmentation, limited bargaining power, price volatility vulnerability, and limited capacity for quality investment or productivity improvement. These smallholder income vulnerability issues create both social sustainability concerns for responsible sourcing programs and supply reliability risks for downstream coconut product manufacturers.
Market Segmentation
By Product Type
Coconut oil retains the leading product market share, though its proportional share is projected to decline as faster-growing categories including coconut water and coconut milk gain share. Coconut water is the fastest-growing product category, driven by its mainstream beverage market penetration across North America, Europe, and increasingly Asia Pacific, supported by growing brand investment, retail distribution expansion, and new product format innovation including coconut water-based functional beverages and sparkling formats.
By Nature
Conventional coconut products retain the majority market share reflecting their dominance in industrial and mainstream food manufacturing applications. Organic coconut products are growing substantially faster, supported by premiumization trends, expanding organic certification infrastructure across producing countries, and strong consumer demand within natural and organic retail channels in developed markets.
By Application
Competitive Landscape
The global coconut products market features a combination of large established coconut processing companies in major producing countries with integrated supply chain control from plantation through finished product, global food and beverage multinationals with coconut product lines and brand investments, and a growing cohort of premium coconut product brands built specifically around coconut’s health and wellness positioning. Competitive dynamics reflect the market’s fragmented supply base and increasingly sophisticated branded consumer products segment.
Regional Analysis
Asia Pacific dominates global coconut production and processing, with Indonesia, the Philippines, India, Sri Lanka, and Thailand collectively accounting for the vast majority of global coconut output and primary processing activity. However, North America and Europe represent the highest-value consumption markets for premium coconut products, driving substantial import demand and branded product revenue growth despite their lack of domestic coconut production.
Emerging Market Trends
Coconut Water Functional Beverage Innovation
Major coconut water brands are innovating beyond plain coconut water into functional beverage extensions including coconut water-based electrolyte sports drinks, protein-enriched coconut water, sparkling coconut water, and coconut water blended with fruit juices and botanical extracts. These product innovations are expanding coconut water’s usage occasions beyond hydration into recovery, relaxation, and adult beverage mixing applications, broadening the category’s growth potential beyond the current core wellness consumer base.
Sustainable Sourcing and Smallholder Farmer Support Programs
Growing brand and retailer investment in sustainable coconut sourcing programs, including farmer training in good agricultural practices, replanting support finance programs, fair trade and organic certification facilitation, and direct farmer sourcing relationships, is improving smallholder farmer livelihoods while strengthening supply chain resilience and transparency. Leading coconut product companies are developing traceability systems enabling consumer-facing origin and sustainability claim substantiation.
Coconut-Based Plant Dairy Alternatives Format Expansion
Continued innovation in coconut-based dairy alternative product formats, including coconut milk yogurt, coconut-based frozen desserts, coconut cream cheese alternatives, and barista-grade coconut milk blends formulated for stable foaming and coffee compatibility, is expanding coconut’s presence across the plant-based dairy aisle. Hybrid coconut-nut and coconut-oat blends are additionally emerging as formulation approaches optimizing creaminess, flavor, and nutritional profile within the competitive plant dairy category.
Coconut Sugar and Natural Sweetener Category Growth
Rising consumer demand for natural sugar alternatives with lower glycemic index perception is driving growth in coconut sugar, coconut nectar, and coconut syrup product categories, positioned as minimally processed natural sweeteners for baking, beverages, and sweetening applications. Coconut sugar’s mineral content, lower glycemic response, and caramel-like flavor profile appeal to health-conscious consumers seeking alternatives to refined white sugar within clean label food product formulations.
Coconut Shell Activated Carbon and Circular Economy Applications
Growing industrial demand for coconut shell activated carbon, valued for its high micropore content, hardness, and renewable sustainability credentials, is creating a valuable circular economy outlet for coconut shell waste from processing operations. Applications in drinking water purification, air filtration, gold recovery, and food and beverage decolorization are expanding as environmental regulation tightening and sustainability-driven substitution of coal-based activated carbon drive demand for coconut-derived alternatives.
Key Companies in the Global Coconut Products Market
-
Vita Coco Company
-
Zico (The Coca-Cola Company)
-
Franklin Baker Company
-
Marico Limited
-
Cargill Incorporated
-
Thai Coconut Public Company
-
PT Sambu Group
-
Celebes Coconut Corporation
-
Nutiva Inc.
-
Taste Nirvana International
-
Regional Coconut Processing Cooperatives and Producers
Report Target Audience
-
Coconut Product Manufacturers and Processors
-
Food and Beverage Companies
-
Personal Care and Cosmetics Manufacturers
-
Agricultural Commodity Traders
-
Investment and Private Equity Firms
-
Government Agricultural and Trade Policy Agencies
-
Management and Strategy Consultants
-
Academic and Agricultural Research Institutions
Market Segmentation Summary
By Product Type
-
Coconut Oil
-
Coconut Water
-
Coconut Milk & Cream
-
Desiccated Coconut & Flour
-
Coconut Sugar & Syrups
-
Coir & Industrial Products
-
Other Coconut Products
By Nature
-
Conventional
-
Organic
By Application
-
Food & Beverage
-
Personal Care & Cosmetics
-
Industrial & Horticultural
-
Pharmaceutical & Nutraceutical
By Region
-
Asia Pacific
-
North America
-
Europe
-
Latin America
-
Middle East & Africa
About GMI Reports
GMI Reports is a premier market intelligence and research organization providing data-driven insights and strategic analysis across global agriculture, food, beverage, and consumer goods markets. Our research empowers producers, brands, and investors to navigate the evolving coconut products landscape with confidence. For the Coconut Products Market report and related research, visit www.gmigreports.com or contact our research team for customized intelligence solutions.
www.gmigreports.com