MARKET RESEARCH REPORT
United Kingdom Broth Market
Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
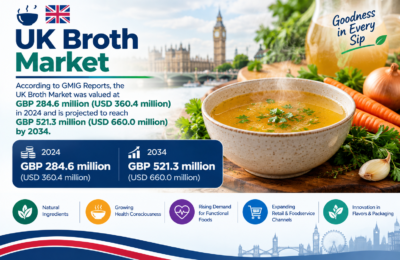
The United Kingdom broth market was valued at approximately GBP 284.6 million (USD 360.4 million) in 2024 and is projected to grow at a compound annual growth rate (CAGR) of approximately 6.2%, reaching GBP 521.3 million (USD 660.0 million) by 2034, according to GMI Reports. The UK broth market encompasses liquid stocks, broths, and bouillons serving as cooking ingredients and increasingly as standalone health beverages, and has experienced notable structural transformation driven by the convergence of growing bone broth wellness consumption, clean label cooking ingredient demand, and the mainstream premiumisation of everyday food products within the UK’s sophisticated grocery retail environment.
The UK broth market has benefited significantly from the bone broth wellness trend, which gained substantial momentum as growing consumer awareness of bone broth’s collagen, amino acid, glycine, and mineral content drove adoption as a gut health, joint health, and immune support functional beverage. This wellness positioning has elevated the broth category’s average selling price, consumer engagement, and retail shelf prominence beyond the utilitarian cooking ingredient positioning that historically defined the category’s commercial dynamics.
The market is additionally shaped by UK consumers’ growing demand for clean label, reduced sodium, organic, and free-range certified broth products reflecting broader food transparency and provenance consciousness trends. Premium broth brands positioning around traceable British-sourced ingredients, traditional slow-cooking methods, and certified welfare and sustainability credentials have achieved meaningful market share growth within the specialist health food, online direct-to-consumer, and premium grocery channels, challenging established ambient stock cube and powder format incumbents.
Market Overview
The United Kingdom broth market encompasses liquid ready-to-use broths and stocks in chilled and ambient formats, concentrated liquid stocks, stock cubes and tablets, powder and granule stock products, bone broth wellness beverages in liquid and powder formats, and plant-based and vegan broth and stock alternatives serving the UK’s growing plant-based cooking consumer base. The market is distributed across major grocery multiples, specialist health food retailers, online grocery and direct-to-consumer channels, and foodservice wholesale channels serving professional kitchens and catering operations.
The UK broth category sits at the intersection of several significant consumer trend currents. The clean label food movement’s emphasis on ingredient simplicity, recognizable components, and reduced additive content is driving category reformulation investment among established broth brands seeking to retain mainstream grocery listing relevance alongside premium clean label challengers. The gut health and functional food movement’s evidence base growth for collagen-containing bone broth products is supporting premiumisation and health-claim adjacent positioning that commands substantial price premium over ambient cooking stock format alternatives.
UK grocery retailers, particularly Waitrose, Marks & Spencer Food, Sainsbury’s, and the online grocery sector, have invested in premium broth and stock range development and dedicated bone broth product ranging, reflecting strong category velocity in premium format segments and consumer appetite for higher-quality, more provenance-transparent alternatives to traditional stock cube and powder format products that have dominated the category for several decades.
Market Size & Forecast
Market Driving Factors
1. Bone Broth Wellness Trend and Functional Beverage Adoption
The sustained and growing UK consumer wellness movement’s embrace of bone broth as a functional health beverage, supported by growing mainstream media coverage of bone broth’s gut health, collagen, and mineral content benefits, has significantly elevated the broth category’s health credential positioning and consumer engagement beyond traditional cooking ingredient utility. Premium bone broth brands have successfully positioned their products within the functional wellness beverage occasion, commanding price points substantially above traditional cooking stock formats and attracting health-motivated consumers previously outside the category’s core audience.
2. Clean Label and Natural Ingredient Demand
UK consumers’ strong and consistently growing preference for food products with simple, recognizable ingredient declarations and minimal additive content is compelling significant clean label reformulation investment across the broth category, as brands seek to align with consumer expectations for natural, transparently produced cooking ingredients. This clean label imperative has driven MSG removal, artificial flavour elimination, reduced sodium reformulation, and organic ingredient sourcing investment across both established broth brands and premium new entrants.
3. Cooking at Home Culture and Scratch Cooking Revival
The sustained post-pandemic cooking at home behavioral shift, combined with growing UK consumer interest in scratch cooking techniques, restaurant-quality home cooking, and culinary skill development, has elevated cooking stock and broth usage frequency and quality aspiration within the UK home cooking occasion. Social media food content showcasing professional cooking techniques and premium ingredient usage has particularly influenced younger consumer cohorts’ engagement with quality broth products as essential kitchen staples.
4. Gut Health and Collagen Consumer Interest Growth
Rapidly growing UK consumer awareness of gut microbiome health’s systemic wellness importance, combined with mainstream media coverage of collagen’s skin, joint, and connective tissue health benefits, has created significant consumer pull for collagen-rich bone broth products within both cooking ingredient and standalone wellness beverage contexts. While regulatory health claim constraints under UK FSA guidelines limit explicit claim communication, consumer understanding of bone broth’s relevant nutritional composition supports purchasing motivation independently of formal health claim assertion.
5. Plant-Based Broth and Vegan Stock Market Expansion
The UK’s significant and growing plant-based food consumer segment has driven meaningful demand for high-quality vegan and vegetable broth products that deliver the flavour depth and umami satisfaction of traditional meat-based stocks within plant-based cooking applications. Premium liquid vegetable broth formats, including mushroom-based, miso-infused, and umami-forward botanical broth products, have achieved notable retail shelf expansion and consumer trial growth within the UK’s well-developed plant-based food retail environment.
6. Premium Grocery Retail Range Development and Category Elevation
Sustained UK premium grocery retailer investment in broth and stock category range development, including dedicated chilled liquid broth sections, premium bone broth product introduction, and own-label premium stock range upgrades at Waitrose, M&S, and Sainsbury’s Taste the Difference tiers, has created significant category premiumisation momentum. Retailer category investment in broth signals to consumers the product’s elevated status from everyday commodity to premium cooking ingredient deserving of quality differentiation and price aspiration.
Market Restraining Factors
1. Entrenched Stock Cube and Powder Format Incumbency
Knorr, OXO, Bisto, and other established stock cube, tablet, and powder format brands retain enormous UK household penetration, brand recognition, and retail shelf space allocation built over decades of category dominance, creating substantial consumer habit inertia and retailer ranging loyalty that premium liquid and bone broth format entrants must overcome through compelling flavour, convenience, and health differentiation to drive meaningful usage occasion substitution among value-anchored mainstream consumers.
2. Premium Format Price Premium Consumer Resistance
Premium liquid broth and bone broth products command significant price premiums relative to established stock cube and powder format alternatives, creating price sensitivity barriers among mainstream UK grocery consumers facing ongoing household budget pressure from cost-of-living increases. Category premiumisation growth is therefore concentrated within higher-income consumer segments and premium retailer channels, constraining total addressable market breadth for premium format products across the full UK consumer income spectrum.
3. Short Shelf Life of Chilled Liquid Format Products
Premium chilled liquid broth products’ relatively short refrigerated shelf life creates distribution complexity, retail waste management challenges, and consumer planning requirement friction that limits category expansion velocity relative to ambient format competitors offering substantially longer shelf life and simpler storage requirements. These cold chain logistics requirements also constrain geographic distribution reach into food service and independent retail channels lacking sophisticated chilled supply chain infrastructure.
4. Health Claim Regulatory Constraints Under UK FSA
UK Food Standards Agency regulatory requirements governing health and nutrition claim communication on food product packaging limit bone broth brands’ ability to explicitly communicate specific health benefits including joint health, gut health, or collagen synthesis support, requiring careful marketing claim management that moderates the directness with which health-motivated consumer purchase drivers can be addressed in mainstream retail channel product communication.
Market Segmentation
By Product Type
Stock cubes and tablets retain the largest market share reflecting decades of UK household penetration and brand loyalty, but are projected to lose significant proportional share to chilled liquid broth and bone broth formats through the forecast period as category premiumisation and cooking ingredient quality aspiration drive consumer format upgrade behaviour. Bone broth is the fastest-growing category, more than doubling its market share proportion between 2024 and 2034 as wellness beverage and functional nutrition positioning drives mainstream adoption beyond early health enthusiast consumer segments.
By Source
Chicken broth retains the most popular source category, reflecting its broad culinary versatility and universal consumer palatability across everyday cooking applications. Beef and bone-sourced broth is exhibiting the fastest premium market growth, anchored by the bone broth wellness trend’s particular association with beef bone broth’s collagen and mineral content profile. Plant-based and vegetable broth is gaining consistent market share, supported by the UK’s well-developed vegan and flexitarian consumer population.
By Distribution Channel
Competitive Landscape
The UK broth market features a combination of dominant established ambient format brands with decades of retail presence and household penetration, premium liquid broth and bone broth challenger brands leveraging health positioning and clean label credentials, and retail own-label premium range development at the major grocery multiples. Competitive dynamics are evolving rapidly as premium format growth attracts new brand entrants and compels established players toward clean label reformulation.
Regional Analysis (Within the UK)
Broth market activity within the UK exhibits meaningful regional variation in product format preference, with premium liquid and bone broth formats showing stronger penetration in London and the Southeast reflecting higher average income levels and greater health food retail infrastructure density, while traditional stock cube and ambient formats retain stronger relative positions in regional markets outside the capital.
Emerging Market Trends
Bone Broth Subscription and Direct-to-Consumer Brand Growth
A growing cohort of UK bone broth brands are building sustainable direct-to-consumer subscription business models, delivering regular frozen or ambient bone broth deliveries to health-motivated subscriber households and generating recurring revenue that bypasses conventional grocery retail margin and ranging dynamics. These DTC bone broth brands invest heavily in consumer education content, community building, and subscription retention programmes that develop strong brand loyalty among health-motivated consumer segments.
Collagen and Functional Ingredient Co-Fortification Innovation
Several UK broth brands are developing products co-fortified with additional functional ingredients including marine collagen, hyaluronic acid, turmeric, ginger, and adaptogenic botanical extracts alongside the natural collagen content of bone broth, creating enhanced functional nutrition positioning within the wellness beverage occasion. These fortified broth products command premium pricing and occupy a distinctive position at the intersection of functional food and wellness supplement categories.
Regenerative Agriculture and Provenance Storytelling
Leading UK premium bone broth brands are developing compelling regenerative agriculture and traceable provenance narratives, communicating the specific British farm origin, animal welfare certification, and sustainable land management practices underlying their meat-based broth products. This provenance transparency and regenerative agriculture alignment resonates strongly with environmentally conscious UK premium food consumers and supports meaningful price premium maintenance against less provenance-differentiated competitors.
Ready-to-Drink Broth Beverage Format Development
Growing development of convenient ready-to-drink broth beverage formats including single-serve chilled bottles, recyclable cartons, and convenient ambient sachet formats is expanding bone broth consumption occasions beyond the home cooking and preparation context into portable wellness beverage occasions. These convenient formats are supporting broth adoption among busy professionals seeking nutritious, warming alternatives to conventional hot beverage choices within workplace and on-the-go consumption occasions.
Vegan Umami Broth and Botanical Stock Innovation
Significant UK plant-based broth innovation is developing sophisticated umami-forward vegan broth formulations incorporating mushroom, miso, seaweed, nutritional yeast, and fermented ingredient combinations that replicate the flavour depth of traditional meat-based stocks within plant-based and flexitarian cooking applications. These premium vegan broth innovations are attracting both committed plant-based and flexitarian consumers alongside omnivorous cooks seeking flavour quality in vegetable-based cooking occasions.
Key Companies in the UK Broth Market
-
Knorr (Unilever UK)
-
OXO (Premier Foods)
-
Baxters Food Group
-
Borough Broth Co.
-
Marigold Health Foods (Bouillon)
-
Ossa Organic / The Pressery
-
Waitrose (Own Label Premium)
-
Marks & Spencer Food (Own Label)
-
Fody Food Co. (UK)
-
Pure Bone Broth / Naturelly
-
Sainsbury’s Taste the Difference (Own Label)
Report Target Audience
-
Broth and Stock Brand Owners and Manufacturers
-
Grocery Retailers and Category Managers
-
Health Food Retailers and Online Platforms
-
Investment and Private Equity Firms
-
Food Ingredient and Flavour Suppliers
-
Direct-to-Consumer Food Brand Operators
-
Management and Strategy Consultants
-
Academic Researchers in Consumer Food Science and Nutrition
Market Segmentation Summary
By Product Type
-
Stock Cubes & Tablets
-
Liquid Broth & Stock (Chilled)
-
Bone Broth (Liquid & Powder)
-
Powder & Granule Stock
-
Concentrated Liquid Stock
By Source
-
Chicken
-
Beef & Bone
-
Vegetable & Plant-Based
-
Fish & Seafood
-
Lamb & Other Meat
By Distribution Channel
-
Supermarkets & Grocery Multiples
-
Online & Direct-to-Consumer
-
Health Food & Specialty Retail
-
Foodservice & Wholesale
By Region (Within the UK)
-
London & Southeast England
-
Midlands & East England
-
Northwest England
-
Scotland
-
Wales & Southwest England
-
Northern Ireland & Northeast
About GMI Reports
GMI Reports is a premier market intelligence and research organization providing data-driven insights and strategic analysis across global food, beverage, and consumer health markets. Our research empowers brands, retailers, and investors to navigate the evolving broth market landscape with confidence. For the United Kingdom Broth Market report and related research, visit www.gmigreports.com or contact our research team for customized intelligence solutions.
www.gmigreports.com