MARKET RESEARCH REPORT
United States Automotive Rain Sensor Market
Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
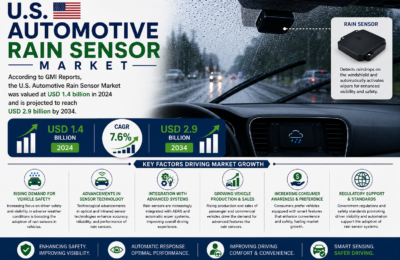
The United States automotive rain sensor market has entered a phase of steady and durable expansion, propelled by rising adoption of advanced driver assistance systems (ADAS), tightening vehicle safety expectations, and the growing integration of automatic wiper and visibility management functions into mainstream trim packages. According to GMI Reports, the market was valued at USD 1.4 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 7.6%, reaching USD 2.9 billion by 2034.
Growth is being reinforced by the migration of rain-sensing technology from a premium convenience feature to a near-standard specification across compact, mid-size, and full-size passenger vehicles. Optical and capacitive sensor architectures are increasingly bundled with forward-facing camera modules and humidity/light sensing clusters, allowing OEMs to consolidate windshield-mounted electronics while reducing per-unit bill-of-materials costs.
Electrification and the parallel build-out of Level 2 and Level 2+ driver-assistance suites are creating additional attachment opportunities, since rain sensors increasingly feed camera-cleaning and sensor-fusion routines rather than functioning as a stand-alone wiper trigger. Meanwhile, aftermarket retrofit demand is gaining traction among fleet operators and ride-hailing vehicle owners seeking to upgrade older vehicles with automatic wiper functionality.
Market Overview
The United States automotive rain sensor market encompasses the design, manufacture, and integration of optical, capacitive, and infrared-based sensing modules that detect moisture on a vehicle’s windshield and automatically actuate wiper systems. These modules are typically mounted behind the windshield near the rearview mirror and are increasingly co-packaged with ambient light sensors, humidity sensors, and forward-facing ADAS cameras.
Rain sensors serve a dual role within the modern vehicle electrical architecture: a comfort and convenience function that reduces manual wiper engagement, and an increasingly safety-critical input that supports automatic emergency braking, lane-keeping, and camera-based perception systems during adverse weather. Tier 1 suppliers have responded by developing multi-sensor modules that combine several environmental sensing functions on a single circuit board, reducing complexity for OEM integration.
Domestic demand is concentrated among the leading US-based OEMs and their supplier networks in the Midwest and Southeast, while a growing share of unit volume is tied to vehicles assembled in Mexico and Canada for the North American market. Passenger cars and light trucks/SUVs together account for the substantial majority of installed units, with commercial van and light-duty truck fleets representing a fast-growing secondary base.
Market Size & Forecast
Market Driving Factors
1. Expanding ADAS Integration and Sensor Fusion
Rain sensors are increasingly wired into camera-cleaning, lane-keeping, and automatic emergency braking subsystems rather than operating as isolated wiper triggers. As automakers push Level 2 and Level 2+ systems deeper into mainstream trims, rain-sensing hardware is being specified earlier in vehicle programs, lifting attachment rates across non-luxury segments.
2. Federal and State Vehicle Safety Standards
The National Highway Traffic Safety Administration continues to encourage the inclusion of visibility-enhancing technologies as part of broader crash-avoidance rulemaking. Several state-level fleet procurement guidelines now favor vehicles equipped with automatic wiper and visibility systems, reinforcing supplier confidence in sustained specification demand across commercial and municipal fleets.
3. Growth of Electric and Software-Defined Vehicle Platforms
Electric vehicle platforms are being engineered around consolidated sensor clusters and centralized compute architectures, creating an opening for multi-function modules that combine rain, light, and humidity sensing. Software-defined vehicle strategies among major US OEMs are accelerating the replacement cycle for legacy single-function rain sensors with networked, over-the-air-updatable modules.
4. Rising Consumer Expectation for Convenience Features
Automatic wiper activation has moved from a luxury differentiator to an expected feature among US new-vehicle buyers, mirroring broader consumer demand for hands-free and automated comfort functions. Survey data from dealership networks indicates rain-sensing wipers now rank among the most frequently requested convenience options in mid-tier trim upgrades.
5. Aftermarket and Fleet Retrofit Demand
Ride-hailing operators, delivery fleets, and commercial vehicle owners are increasingly retrofitting older vehicles with rain-sensing wiper kits to reduce driver distraction and insurance exposure. This aftermarket channel, while smaller than OEM volumes, is growing at a faster relative pace as fleet operators standardize safety equipment across mixed-age vehicle rosters.
Market Restraining Factors
1. Sensor and Semiconductor Component Cost Pressures
Global semiconductor supply constraints in recent years have periodically elevated component costs for optical and capacitive sensing modules. Tier 1 suppliers continue to absorb variable input costs for precision optics and application-specific integrated circuits, compressing margins on lower-price-point vehicle programs.
2. Windshield Design and Retrofit Complexity
The proliferation of heads-up displays, acoustic laminated glass, and UV-blocking windshield coatings has complicated sensor calibration and mounting standardization. Aftermarket retrofit installations face additional technical hurdles when adapting rain-sensing modules to windshields not originally engineered for sensor integration.
3. Price Sensitivity in Entry-Level Vehicle Segments
Automatic rain-sensing wipers remain optional equipment on a meaningful share of entry-level and budget-trim vehicles sold in the United States. Cost-conscious buyers in this segment frequently forgo the feature, limiting near-term penetration gains despite broader category growth.
4. Calibration and False-Activation Reliability Concerns
Variability in sensor performance under road spray, debris, and extreme temperature conditions has historically generated consumer complaints regarding false wiper activation or delayed response. Suppliers must continue to invest in calibration software and machine-learning-based signal processing to maintain reliability expectations across diverse US climate zones.
Market Segmentation
By Sensor Technology
The United States automotive rain sensor market is segmented by sensor technology into optical, capacitive, and infrared/hybrid systems.
Optical sensors retain the leading share owing to established signal reliability and proven integration with camera-based ADAS modules. Capacitive sensing is gaining ground due to lower unit costs and compatibility with advanced UV-blocking laminated windshields, while infrared and hybrid systems continue to serve niche cold-climate and anti-icing applications.
By Vehicle Type
The market is segmented by vehicle type into passenger cars, light commercial vehicles, and heavy commercial vehicles.
By Sales Channel
Competitive Landscape
The United States automotive rain sensor market is moderately consolidated, dominated by established Tier 1 automotive electronics suppliers with deep OEM integration relationships, alongside a smaller group of specialized sensor manufacturers. The leading five suppliers account for an estimated 55-60% of total market revenues.
Regional Analysis
The Midwest region leads the United States automotive rain sensor market, generating an estimated 34% of total national revenues, reflecting its concentration of OEM assembly plants and Tier 1 supplier operations. Meaningful growth is also occurring in the South and West as vehicle production capacity continues to shift toward these regions.
Emerging Market Trends
Sensor Consolidation and Multi-Function Modules
Suppliers are increasingly combining rain, light, humidity, and forward-camera functions within a single windshield-mounted module, reducing wiring complexity and enabling centralized vehicle compute architectures to process multiple environmental inputs simultaneously.
AI-Enabled Signal Processing
Machine-learning-based calibration is being deployed to reduce false-activation rates and improve droplet-size discrimination, particularly for capacitive and MEMS-based sensor architectures operating in variable US climate conditions.
Electrification-Driven Redesign
Electric vehicle platforms are prompting redesigned sensor mounting and power architectures, with several US-market EV programs adopting networked, over-the-air-updatable sensor firmware as part of broader software-defined vehicle strategies.
Aftermarket Retrofit Expansion
Growing fleet and ride-hailing demand is expanding the aftermarket retrofit channel, with several specialized suppliers introducing universal rain-sensor wiper kits designed for installation across a broad range of vehicle makes and models without OEM-level integration.
Key Companies in the United States Automotive Rain Sensor Market
-
Robert Bosch LLC
-
Continental AG (US)
-
Denso International America
-
Valeo North America
-
HELLA Inc.
-
Vishay Intertechnology
-
ZF Group North America
-
Melexis Inc.
-
onsemi
-
Uro Sensor Solutions
-
Other Regional and Aftermarket Suppliers
Report Target Audience
-
Automotive OEMs and Tier 1/Tier 2 Suppliers
-
Investment and Private Equity Firms
-
Sensor and Semiconductor Component Manufacturers
-
Fleet Operators and Commercial Vehicle Owners
-
Regulatory and Vehicle Safety Policy Bodies
-
Management Consulting and Advisory Firms
-
Academic Researchers in Automotive Engineering
-
Aftermarket Parts Distributors and Retailers
Market Segmentation Summary
By Sensor Technology
-
Optical
-
Capacitive
-
Infrared/Hybrid
By Vehicle Type
-
Passenger Cars
-
Light Commercial Vehicles
-
Heavy Commercial Vehicles
By Sales Channel
-
Original Equipment Manufacturer (OEM)
-
Aftermarket
By Region
-
Midwest
-
South
-
West
-
Northeast
-
Mountain
-
Other Regions
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com
© 2026 GMI Reports. All Rights Reserved. Unauthorized reproduction or distribution is prohibited.