MARKET RESEARCH REPORT
Biotech Pharma Clinical Trial Services Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
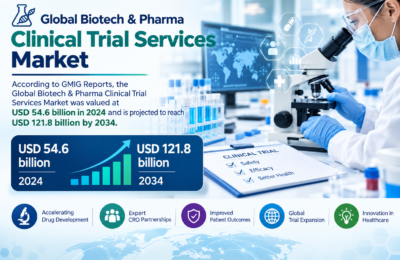
The global biotech and pharma clinical trial services market has sustained robust growth, driven by intensifying pharmaceutical and biotechnology research and development investment, accelerating adoption of decentralized clinical trial models, and continued outsourcing of complex trial operations to specialized contract research organizations. According to GMI Reports, the market was valued at USD 54.6 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 8.4%, reaching USD 121.8 billion by 2034.
Growth is being reinforced by an approaching wave of major pharmaceutical patent expirations driving intensified pipeline investment and outsourced trial activity, growing clinical trial complexity associated with precision medicine and biologics development requiring specialized CRO expertise, and expanding adoption of decentralized and hybrid trial models that improve patient recruitment and retention while reducing overall trial timelines and costs.
Oncology continues to represent the largest therapeutic area by clinical trial services revenue, reflecting the sheer volume and complexity of cancer drug development pipelines globally. Full-service outsourcing models continue to dominate sponsor procurement strategies, though functional service provider arrangements offering more flexible, specialized resourcing are gaining share as sponsors seek greater operational control alongside outsourced expertise.
Market Overview
The global biotech and pharma clinical trial services market encompasses the full spectrum of outsourced services supporting drug and biologic development, including protocol design, patient recruitment and retention, clinical site management, regulatory affairs support, data management and biostatistics, and pharmacovigilance and post-marketing surveillance. Contract research organizations serve as the primary service delivery mechanism, offering pharmaceutical and biotechnology sponsors access to specialized trial execution expertise and global site networks without maintaining extensive in-house clinical operations infrastructure.
Clinical trial complexity continues to intensify across the industry, driven by the growing prevalence of precision medicine approaches requiring biomarker-stratified patient populations, expanding biologics and cell and gene therapy development pipelines, and increasingly rigorous global regulatory documentation requirements. This complexity increasingly necessitates specialized CRO expertise that many sponsor organizations, particularly smaller biotechnology companies, cannot cost-effectively maintain internally.
Decentralized clinical trial models incorporating remote patient monitoring, telehealth-based site visits, and direct-to-patient drug shipment continue to gain adoption momentum, improving patient recruitment reach and retention rates while addressing long-standing clinical trial diversity and accessibility challenges. Major CROs continue substantial technology investment in digital trial management platforms and artificial intelligence-powered patient recruitment tools to differentiate service offerings and improve trial execution efficiency.
Market Size & Forecast
Market Driving Factors
1. Approaching Pharmaceutical Patent Cliff and Pipeline Investment
A significant wave of upcoming major pharmaceutical patent expirations is intensifying sponsor company pipeline investment and driving increased outsourced clinical trial activity, as pharmaceutical companies race to develop and bring new therapies to market ahead of revenue loss from generic and biosimilar competition.
2. Growing Clinical Trial Complexity from Precision Medicine
The increasing prevalence of precision medicine and biomarker-driven drug development approaches is driving demand for specialized CRO expertise in complex trial design, patient stratification, and companion diagnostic coordination that exceeds the internal capabilities of many sponsor organizations.
3. Expansion of Decentralized and Hybrid Clinical Trial Models
Continued adoption of decentralized clinical trial models incorporating remote monitoring, telehealth visits, and direct-to-patient drug shipment is improving patient recruitment reach and retention rates, driving CRO investment in digital trial management platforms and creating new service revenue opportunities.
4. Rising Biotechnology Company Reliance on Outsourced Trial Expertise
The growing number of smaller, venture-funded biotechnology companies advancing drug candidates through clinical development continues to expand demand for full-service CRO outsourcing, as these organizations typically lack the internal clinical operations infrastructure of large pharmaceutical companies.
5. Growing Clinical Trial Activity in Emerging Markets
Expanding clinical trial activity across Asia Pacific and other emerging markets, driven by large patient populations, improving clinical research infrastructure, and cost advantages relative to established Western markets, continues to create new growth opportunities for CROs with global site network capabilities.
Market Restraining Factors
1. Patient Recruitment and Retention Challenges
Clinical trial patient recruitment and retention remain persistent operational challenges across the industry, with trial delays attributable to enrollment shortfalls continuing to affect sponsor timelines and budgets despite growing investment in digital recruitment and decentralized trial technologies.
2. Rising Clinical Trial Costs and Budget Pressure
Escalating overall clinical trial costs, driven by increasing regulatory documentation requirements and trial complexity, continue to create budget pressure for sponsor organizations, occasionally constraining pipeline investment scope or driving cost-focused vendor selection processes.
3. Regulatory Fragmentation Across International Markets
Considerable variability in clinical trial regulatory requirements across different international jurisdictions creates compliance complexity for global multi-region trials, requiring CROs to maintain extensive region-specific regulatory expertise and occasionally slowing global trial execution timelines.
4. CRO Industry Consolidation and Capacity Constraints
Ongoing consolidation among major contract research organizations has concentrated significant market capacity among a smaller number of large players, occasionally creating capacity constraints and pricing power dynamics that can affect smaller sponsor organizations’ access to specialized trial services.
Market Segmentation
By Service Type
The biotech and pharma clinical trial services market is segmented by service type into full-service clinical development (end-to-end CRO) and functional service provider (FSP)/resourcing models.
Full-service outsourcing retains a substantial share given comprehensive trial execution capability, while functional service provider models are gaining share fastest as sponsors increasingly seek flexible, specialized resourcing arrangements that preserve greater operational control over trial management.
By Trial Phase
The market is segmented by trial phase into Phase I, Phase II/III, and Phase IV/real-world evidence & post-marketing.
By Therapeutic Area
Competitive Landscape
The global biotech and pharma clinical trial services market remains highly concentrated, with a small number of large multinational contract research organizations commanding the substantial majority of market revenue through comprehensive global site networks and full-service capabilities. The leading five companies account for an estimated 55-60% of total global market revenues.
Regional Analysis
North America leads the global biotech and pharma clinical trial services market, generating an estimated 43% of total global revenues, supported by concentrated pharmaceutical industry R&D spending and the world’s largest CRO headquarters base. Asia Pacific represents the fastest-growing region, driven by large patient populations, improving clinical research infrastructure, and favorable cost economics in China and India.
Emerging Market Trends
AI-Powered Patient Recruitment and Trial Design
CROs are increasingly deploying artificial intelligence tools for patient recruitment optimization, protocol design refinement, and predictive trial risk assessment, aiming to reduce enrollment timelines and improve overall trial execution efficiency across increasingly complex study designs.
Expansion of Decentralized Trial Infrastructure
Continued investment in decentralized clinical trial infrastructure, including remote monitoring technology, telehealth integration, and direct-to-patient logistics capabilities, is expanding trial accessibility and improving patient diversity within clinical research populations.
Growth in Cell and Gene Therapy Trial Specialization
Rapid expansion of cell and gene therapy development pipelines is driving demand for CRO services with specialized expertise in the unique manufacturing, logistics, and regulatory requirements associated with these advanced therapy modalities, distinct from traditional small-molecule drug development.
Real-World Evidence Integration Expansion
Growing sponsor and regulatory interest in real-world evidence generation to support post-marketing surveillance and label expansion applications is expanding CRO service offerings beyond traditional pre-approval trial phases into ongoing real-world data collection and analysis services.
Key Companies in the Biotech Pharma Clinical Trial Services Market
-
IQVIA Holdings Inc.
-
Labcorp Holdings Inc.
-
ICON plc
-
Thermo Fisher Scientific Inc. (PPD)
-
Parexel International Corporation
-
Syneos Health Inc.
-
Charles River Laboratories International
-
Medpace Holdings Inc.
-
Fortrea Holdings Inc.
-
WuXi AppTec Co.
-
Other Regional and Specialized CROs
Report Target Audience
-
Pharmaceutical and Biotechnology Companies
-
Contract Research Organizations (CROs)
-
Investment and Venture Capital Firms
-
Clinical Trial Technology and Software Providers
-
Regulatory and Drug Approval Bodies
-
Management Consulting and Advisory Firms
-
Clinical Research Site Networks
-
Academic Researchers in Drug Development and Clinical Research
Market Segmentation Summary
By Service Type
-
Full-Service Clinical Development (End-to-End CRO)
-
Functional Service Provider (FSP)/Resourcing
By Trial Phase
-
Phase I
-
Phase II/III
-
Phase IV/RWE & Post-Marketing
By Therapeutic Area
-
Oncology
-
Rare & Orphan Diseases
-
Cardiovascular & Metabolic
-
Infectious Diseases
-
Other Therapeutic Areas
By Region
-
North America
-
Europe
-
Asia Pacific
-
Latin America
-
Middle East & Africa
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com