MARKET RESEARCH REPORT
Solar Panel Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
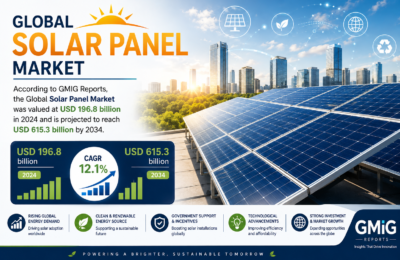
The global solar panel market has sustained strong multi-year momentum, driven by continually falling module costs, expanding utility-scale project pipelines, and intensifying government policy support for renewable energy deployment worldwide. According to GMI Reports, the market was valued at USD 196.8 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 12.1%, reaching USD 615.3 billion by 2034.
Growth is being reinforced by aggressive manufacturing capacity expansion across Asia Pacific, particularly China, which continues to drive global module price declines and improve project economics across residential, commercial, and utility-scale segments. Simultaneously, energy security concerns following recent geopolitical disruptions have accelerated national solar deployment targets across Europe, India, and the Middle East, broadening demand beyond traditionally dominant markets.
Technological advancement in cell architecture, including the transition toward higher-efficiency TOPCon and heterojunction (HJT) cell designs, is improving panel output per unit area and supporting continued cost-per-watt reductions. Meanwhile, trade policy developments, including tariffs and anti-dumping measures in key import markets, continue to reshape global manufacturing footprint decisions among leading module producers.
Market Overview
The global solar panel market encompasses the manufacturing and deployment of photovoltaic modules that convert sunlight directly into electricity, spanning crystalline silicon, thin-film, and emerging cell technologies. Core end-use applications include utility-scale ground-mounted solar farms, commercial and industrial rooftop installations, and residential distributed generation systems.
China continues to dominate global module manufacturing capacity, supported by vertically integrated supply chains spanning polysilicon, wafer, cell, and module production. However, manufacturing diversification is accelerating as the United States, India, and select European markets incentivize domestic production capacity through tax credits and local content requirements aimed at reducing supply chain concentration risk.
Utility-scale solar continues to represent the largest single application segment globally, driven by declining levelized cost of electricity that increasingly positions solar as the lowest-cost new-build generation source in many markets. Residential and commercial rooftop segments are simultaneously benefiting from expanding net metering policies, battery storage co-adoption, and rising retail electricity prices that improve consumer payback economics.
Market Size & Forecast
Market Driving Factors
1. Continued Decline in Module Manufacturing Costs
Sustained overcapacity within global polysilicon and module manufacturing, combined with ongoing technological efficiency improvements, continues to drive per-watt production costs lower, improving project economics and expanding solar’s competitiveness against conventional generation sources across an increasing number of markets.
2. Expanding Utility-Scale Project Pipelines
Utility developers and independent power producers continue to expand gigawatt-scale solar project pipelines globally, supported by declining levelized cost of electricity and growing corporate power purchase agreement demand from technology and industrial companies seeking to meet clean energy procurement commitments.
3. Strengthening Government Policy and Incentive Frameworks
National renewable energy targets, tax credit programs, and streamlined permitting initiatives across major markets including the United States, European Union member states, India, and China continue to provide strong policy tailwinds supporting sustained solar capacity additions through the forecast period.
4. Rising Energy Security Priorities Following Geopolitical Disruption
Recent energy supply disruptions have accelerated national strategies to reduce fossil fuel import dependence, with several European and Asian governments materially increasing solar deployment targets as part of broader energy independence and grid resilience strategies.
5. Growing Co-Adoption with Battery Energy Storage Systems
Increasing pairing of solar installations with battery storage systems is improving project value propositions by enabling greater grid dispatch flexibility and higher self-consumption rates, expanding solar’s addressable market across both utility-scale and distributed generation segments.
Market Restraining Factors
1. Trade Tariffs and Anti-Dumping Measures
Escalating trade barriers, including tariffs and anti-dumping duties imposed by the United States and other markets on solar cells and modules from certain manufacturing origins, continue to create cost uncertainty and complicate global supply chain planning for module manufacturers and project developers.
2. Grid Interconnection Queue Delays
Utility-scale solar project development in several major markets continues to face significant grid interconnection queue backlogs and transmission capacity constraints, delaying project commissioning timelines and creating development risk for large-scale solar pipelines.
3. Manufacturing Overcapacity and Margin Pressure
Persistent global module manufacturing overcapacity, particularly concentrated in China, has driven module prices toward or below production costs for many manufacturers, compressing industry-wide profitability and triggering periodic consolidation and capacity rationalization across the supply chain.
4. Land Use and Permitting Constraints for Utility-Scale Projects
Large-scale ground-mounted solar projects increasingly face land use competition, environmental permitting requirements, and local community opposition in certain markets, creating development timeline uncertainty and, in some cases, constraining utility-scale project siting options.
Market Segmentation
By Technology
The solar panel market is segmented by technology into crystalline silicon (monocrystalline and polycrystalline) and thin-film.
Monocrystalline silicon retains the dominant and growing market share given superior efficiency and continued cost convergence with polycrystalline alternatives, while thin-film technology continues to gain share in specialized applications including building-integrated photovoltaics and utility-scale projects prioritizing temperature performance.
By Installation Type
The market is segmented by installation type into ground-mounted, rooftop, and floating solar installations.
By Application
Competitive Landscape
The global solar panel market remains highly competitive and moderately consolidated, dominated by large vertically integrated Chinese manufacturers alongside a smaller group of specialized producers based in the United States, South Korea, and other regions. The leading ten manufacturers account for an estimated 65-70% of total global module shipments.
Regional Analysis
Asia Pacific leads the global solar panel market, generating an estimated 52% of total global revenues, supported by dominant manufacturing capacity concentration and rapidly expanding domestic deployment across China and India. North America and Europe represent significant secondary markets, with growth increasingly supported by domestic manufacturing incentives and energy security-driven deployment targets.
Emerging Market Trends
Transition Toward TOPCon and Heterojunction Cell Technology
Manufacturers are rapidly transitioning production capacity from conventional PERC cell technology toward higher-efficiency TOPCon and heterojunction (HJT) architectures, driving improved module output and supporting continued cost-per-watt reductions across the industry.
Bifacial Module Adoption Growth
Bifacial panels capable of capturing reflected light on both sides are gaining share across utility-scale ground-mounted projects, offering improved energy yield per installed watt and increasingly favorable project-level economics for large-scale developers.
Manufacturing Diversification Beyond China
Growing geopolitical and trade policy pressures are accelerating manufacturing capacity investment across the United States, India, and Southeast Asia, as module producers and project developers seek to diversify supply chains and mitigate tariff exposure.
Floating Solar Deployment Expansion
Floating solar installations on reservoirs and water bodies are gaining traction as a land-efficient deployment option, particularly in densely populated markets across Asia, offering improved panel cooling performance alongside reduced water evaporation as a secondary benefit.
Key Companies in the Solar Panel Market
-
LONGi Green Energy Technology Co.
-
JinkoSolar Holding Co.
-
Trina Solar Co.
-
JA Solar Technology Co.
-
Canadian Solar Inc.
-
First Solar Inc.
-
Hanwha Q CELLS Co.
-
Risen Energy Co.
-
REC Group
-
Tata Power Solar Systems Ltd.
-
Other Regional and Emerging Manufacturers
Report Target Audience
-
Solar Module Manufacturers and Component Suppliers
-
Utility Companies and Independent Power Producers
-
Investment and Private Equity Firms
-
Government Energy and Renewable Policy Bodies
-
Engineering, Procurement & Construction (EPC) Firms
-
Management Consulting and Advisory Firms
-
Corporate Sustainability and Procurement Teams
-
Academic Researchers in Renewable Energy Technology
Market Segmentation Summary
By Technology
-
Monocrystalline Silicon
-
Polycrystalline Silicon
-
Thin-Film
By Installation Type
-
Ground-Mounted
-
Rooftop
-
Floating Solar
By Application
-
Utility-Scale
-
Commercial & Industrial
-
Residential
By Region
-
Asia Pacific
-
North America
-
Europe
-
Middle East & Africa
-
Latin America
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com