MARKET RESEARCH REPORT
Medical Smartwatch Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
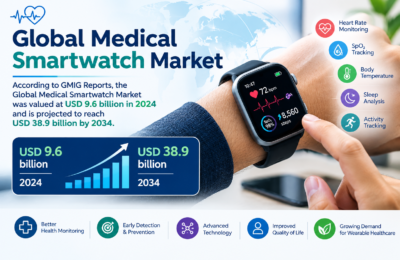
The global medical smartwatch market has entered a phase of rapid expansion as clinical-grade wearable technology increasingly moves from consumer fitness tracking into legitimate chronic disease management and diagnostic-support applications. According to GMI Reports, the market was valued at USD 9.6 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 15.0%, reaching USD 38.9 billion by 2034.
Growth is being reinforced by expanding regulatory clearances for smartwatch-integrated ECG, blood oxygen, and atrial fibrillation detection features, growing healthcare provider integration of wearable-generated patient data into remote patient monitoring and chronic care management programs, and continued advancement toward non-invasive glucose monitoring capabilities that could dramatically expand the category’s addressable diabetes management application.
Medical-grade smartwatches increasingly bridge the gap between consumer wellness devices and traditional clinical diagnostic equipment, with major consumer technology companies pursuing regulatory clearances alongside specialized medical device manufacturers developing dedicated clinical-grade wearables. Healthcare providers increasingly view validated smartwatch health data as a legitimate input for clinical decision-making, particularly in cardiac rhythm monitoring and chronic disease management contexts.
Market Overview
The global medical smartwatch market encompasses wrist-worn wearable devices incorporating regulatory-cleared or clinically validated health monitoring sensors capable of detecting and tracking physiological metrics including electrocardiogram (ECG) readings, blood oxygen saturation, heart rhythm irregularities, blood pressure trends, and sleep quality metrics. The category spans consumer smartwatches with cleared medical features and dedicated clinical-grade wearables designed specifically for chronic disease management and remote patient monitoring applications.
Cardiac monitoring, particularly atrial fibrillation and irregular heart rhythm detection, represents the most mature and widely adopted medical smartwatch application, supported by multiple major regulatory clearances and substantial clinical validation evidence. Diabetes management represents an increasingly important growth application, with continued research and development investment directed toward achieving reliable non-invasive glucose monitoring capabilities that would significantly expand the category’s clinical utility.
The competitive landscape includes major consumer technology companies that have successfully pursued medical device regulatory clearances for smartwatch health features, alongside specialized medical wearable manufacturers focused exclusively on clinical-grade monitoring applications. Healthcare provider integration continues to deepen, with growing numbers of health systems incorporating smartwatch-generated patient data directly into electronic health record systems and remote patient monitoring reimbursement programs.
Market Size & Forecast
Market Driving Factors
1. Expanding Regulatory Clearances for Cardiac Monitoring Features
Continued regulatory clearance expansion for smartwatch-integrated ECG and atrial fibrillation detection capabilities across major markets is strengthening clinical credibility and driving healthcare provider and patient confidence in medical smartwatch cardiac monitoring applications.
2. Growing Integration with Remote Patient Monitoring Programs
Healthcare providers are increasingly incorporating validated smartwatch health data directly into remote patient monitoring programs and chronic disease management protocols, supported by expanding reimbursement pathways that recognize wearable-generated physiological data as legitimate clinical monitoring input.
3. Advancing Non-Invasive Glucose Monitoring Research
Substantial ongoing research and development investment toward achieving reliable non-invasive glucose monitoring capabilities within smartwatch form factors represents a potentially transformative growth catalyst, given the massive global diabetes management market this capability could address if successfully commercialized.
4. Rising Chronic Disease Prevalence and Aging Populations
Growing global prevalence of cardiovascular disease, diabetes, and other chronic conditions requiring continuous monitoring, combined with aging populations in major developed markets, continues to expand the addressable patient population for medical smartwatch adoption.
5. Consumer Technology Company Investment in Medical-Grade Features
Major consumer technology companies continue substantial investment in pursuing medical device regulatory clearances for smartwatch health features, leveraging existing massive consumer device installed bases to rapidly scale medical-grade monitoring capability adoption beyond dedicated medical device channels.
Market Restraining Factors
1. Regulatory Complexity and Lengthy Clearance Timelines
Obtaining medical device regulatory clearance for smartwatch health monitoring features involves rigorous clinical validation and lengthy regulatory review timelines, creating development cost and time-to-market barriers, particularly for smaller manufacturers competing against well-resourced established players.
2. Clinical Accuracy and False Positive/Negative Concerns
Ongoing concerns regarding smartwatch health monitoring accuracy relative to traditional clinical diagnostic equipment, including false positive and false negative detection rates, continue to create clinician caution regarding full integration of wearable-generated data into clinical decision-making without corroborating traditional diagnostic testing.
3. Data Privacy and Health Information Security Concerns
The continuous collection and transmission of sensitive health data through medical smartwatches raises data privacy and cybersecurity concerns, and healthcare data protection regulatory compliance requirements create additional complexity for manufacturers and healthcare provider integration partners.
4. High Device Cost Limiting Broader Patient Access
Premium medical-grade smartwatches continue to carry substantial price points that can limit accessibility for lower-income patient populations who might otherwise benefit most from continuous chronic disease monitoring capabilities, creating health equity considerations for broader category adoption.
Market Segmentation
By Product Grade
The medical smartwatch market is segmented by product grade into consumer smartwatches with cleared medical features and dedicated clinical-grade medical smartwatches.
Consumer smartwatches with cleared medical features retain the larger share given massive existing installed device bases and brand recognition, while dedicated clinical-grade devices are gaining share as healthcare providers increasingly seek purpose-built monitoring solutions for specific chronic disease management protocols.
By Application
The market is segmented by application into cardiac monitoring, diabetes management, sleep disorder monitoring, and other chronic disease applications.
By Distribution Channel
Competitive Landscape
The global medical smartwatch market features intense competition between major consumer technology companies that have secured medical device clearances and specialized medical wearable manufacturers focused on clinical-grade monitoring. The leading five companies account for an estimated 65-70% of total global market revenues.
Regional Analysis
North America leads the global medical smartwatch market, generating an estimated 41% of total global revenues, supported by favorable regulatory clearance pathways, high consumer technology adoption, and expanding remote patient monitoring reimbursement infrastructure. Europe and Asia Pacific represent significant secondary markets, with Asia Pacific showing the fastest growth driven by expanding healthcare digitization initiatives.
Emerging Market Trends
Non-Invasive Glucose Monitoring Development
Multiple manufacturers continue intensive research and development investment toward achieving reliable non-invasive blood glucose monitoring within smartwatch form factors, representing a potentially transformative development for diabetes management should clinical-grade accuracy be achieved and regulatory clearance obtained.
AI-Powered Predictive Health Analytics
Growing integration of artificial intelligence capabilities within medical smartwatches is enabling more sophisticated predictive health analytics, moving beyond simple metric tracking toward early warning detection for potential cardiac events and other acute health episodes.
Deeper Electronic Health Record Integration
Healthcare systems are increasingly developing direct integration pathways between medical smartwatch data streams and electronic health record systems, enabling clinicians to access continuous patient monitoring data alongside traditional clinical documentation for more comprehensive care management.
Expansion into Mental Health and Stress Monitoring
Medical smartwatch manufacturers are increasingly incorporating stress, mood, and mental health monitoring capabilities alongside traditional physical health metrics, reflecting growing clinical and consumer interest in holistic wellness monitoring that addresses both physical and psychological health dimensions.
Key Companies in the Medical Smartwatch Market
-
Apple Inc.
-
Samsung Electronics Co.
-
Garmin Ltd.
-
Fitbit (Google LLC)
-
Withings SA
-
AliveCor Inc.
-
Biotricity Inc.
-
Philips Healthcare (Koninklijke Philips)
-
Huawei Technologies Co.
-
Movano Health Inc.
-
Other Regional and Emerging Medical Wearable Companies
Report Target Audience
-
Medical Device and Consumer Electronics Manufacturers
-
Hospitals and Healthcare Provider Networks
-
Investment and Venture Capital Firms
-
Healthcare Payers and Insurance Providers
-
Medical Device Regulatory Bodies
-
Management Consulting and Advisory Firms
-
Remote Patient Monitoring Platform Operators
-
Academic Researchers in Digital Health and Cardiology
Market Segmentation Summary
By Product Grade
-
Consumer Smartwatches with Medical Features
-
Dedicated Clinical-Grade Medical Smartwatches
By Application
-
Cardiac Monitoring (ECG, Arrhythmia Detection)
-
Diabetes Management & Glucose Monitoring
-
Sleep Disorder Monitoring
-
Other Chronic Disease Applications
By Distribution Channel
-
Consumer Electronics Retail & E-Commerce
-
Healthcare Provider & Hospital Procurement
-
Pharmacy & Specialty Medical Retail
By Region
-
North America
-
Europe
-
Asia Pacific
-
Latin America
-
Middle East & Africa
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com