MARKET RESEARCH REPORT
Commercial Flooring Tiles Market
Global Insights, Analysis & Forecasts to 2034
Published by GMI Reports | www.gmigreports.com
Executive Summary
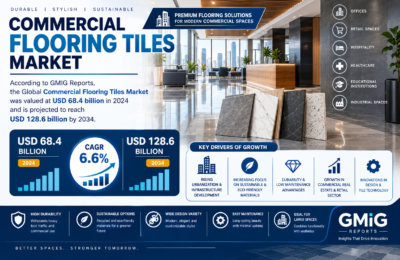
The global commercial flooring tiles market has sustained steady expansion, underpinned by continued growth in office, retail, hospitality, and healthcare construction, combined with rising renovation and replacement cycles across aging commercial building stock worldwide. According to GMI Reports, the market was valued at USD 68.4 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of approximately 6.5%, reaching USD 128.6 billion by 2034.
Growth is being reinforced by increasing specification of porcelain and vitrified tile products for their superior durability and low-maintenance performance in high-traffic commercial environments, rapid advancement in digital printing technology enabling wood- and stone-effect tile aesthetics at lower cost, and intensifying building sustainability certification requirements favoring recycled-content and low-emission tile products.
Asia Pacific continues to anchor global manufacturing capacity and consumption, supported by extensive commercial construction activity across China and India, while North American and European markets increasingly emphasize premium large-format porcelain tiles and luxury vinyl tile alternatives within office and hospitality renovation projects. Replacement and renovation activity, rather than new construction, increasingly represents the primary demand driver across mature developed markets.
Market Overview
The global commercial flooring tiles market encompasses ceramic, porcelain, vitrified, and luxury vinyl tile products specified for use in offices, retail environments, healthcare facilities, hospitality venues, and educational institutions. Core product attributes prioritized in commercial specification include durability under heavy foot traffic, slip resistance, ease of maintenance, and increasingly, sustainability credentials including recycled material content and low volatile organic compound emissions.
Porcelain and vitrified tiles continue to gain specification preference over standard ceramic tiles in premium commercial applications, owing to superior density, water resistance, and durability characteristics suited to high-traffic environments. Advances in digital inkjet printing technology have enabled manufacturers to replicate natural wood, stone, and concrete aesthetics on durable tile substrates, expanding design flexibility while maintaining the maintenance and durability advantages of hard flooring surfaces.
The competitive landscape spans large multinational tile manufacturers with global production and distribution networks, alongside regional and national producers serving domestic commercial construction markets. Building sustainability certification frameworks, including LEED and BREEAM, increasingly influence specification decisions, favoring tile products with documented recycled content, regional sourcing, and lower embodied carbon manufacturing processes.
Market Size & Forecast
Market Driving Factors
1. Sustained Commercial Construction and Renovation Activity
Continued global investment in office, retail, hospitality, and healthcare facility construction and renovation projects sustains structural demand for commercial-grade tile flooring, with replacement and refurbishment activity increasingly representing the primary demand driver across mature developed markets.
2. Growing Preference for Porcelain and Vitrified Tile Products
Commercial building owners and specifiers are increasingly favoring porcelain and vitrified tiles over standard ceramic alternatives given their superior durability, water resistance, and reduced long-term maintenance costs, driving continued premiumization within the overall tile category.
3. Advancements in Digital Printing and Design Customization
Continued improvement in digital inkjet printing technology is enabling manufacturers to produce tiles replicating natural wood, stone, and concrete finishes at increasingly competitive price points, expanding design flexibility for commercial specifiers while retaining the durability benefits of hard tile surfaces.
4. Intensifying Building Sustainability Certification Requirements
Growing adoption of green building certification frameworks including LEED and BREEAM across commercial construction projects is increasing specifier demand for tile products with documented recycled content, low-emission manufacturing, and regional sourcing credentials, favoring manufacturers with established sustainability programs.
5. Expansion of Healthcare and Hospitality Sector Construction
Rising global healthcare infrastructure investment and continued hospitality sector expansion, particularly across Asia Pacific and the Middle East, are creating substantial incremental demand for hygienic, durable, and slip-resistant tile flooring solutions specified for these demanding commercial environments.
Market Restraining Factors
1. Volatile Raw Material and Energy Input Costs
Tile manufacturing remains energy-intensive, and fluctuating natural gas and raw material costs, particularly clay and feldspar inputs, continue to create margin pressure for manufacturers and periodic pricing volatility affecting commercial project procurement budgets.
2. Competition from Alternative Flooring Materials
Luxury vinyl tile and engineered flooring alternatives continue to compete with traditional ceramic and porcelain tiles in commercial applications, offering lower installation costs and faster installation timelines that can appeal to cost- and schedule-sensitive commercial projects.
3. Construction Sector Cyclicality
Commercial construction activity remains sensitive to broader macroeconomic conditions and interest rate cycles, and periods of commercial real estate investment slowdown have historically translated into near-term demand softness for commercial flooring tile products.
4. High Installation Labor Costs and Skilled Labor Shortages
Tile installation requires skilled labor for proper substrate preparation and setting, and rising labor costs combined with skilled tile-setter shortages in several developed markets continue to increase total project costs, occasionally favoring faster-installing alternative flooring materials.
Market Segmentation
By Material Type
The commercial flooring tiles market is segmented by material type into ceramic tiles, porcelain/vitrified tiles, and luxury vinyl tiles (LVT).
Porcelain and vitrified tiles retain the largest and growing share given superior durability performance favored in commercial specification, while standard ceramic tiles gradually cede share as premiumization trends continue across the commercial construction sector.
By End-Use Sector
The market is segmented by end-use sector into offices, retail, hospitality, healthcare, and education.
By Application
Competitive Landscape
The global commercial flooring tiles market remains moderately fragmented, featuring a mix of large multinational tile manufacturers with global distribution networks and numerous regional producers serving domestic commercial construction markets. The leading ten companies account for an estimated 35-40% of total global market revenues.
Regional Analysis
Asia Pacific leads the global commercial flooring tiles market, generating an estimated 46% of total global revenues, supported by extensive commercial construction activity across China and India and the region’s dominant tile manufacturing capacity concentration. North America and Europe represent significant secondary markets, characterized by premium product specification and renovation-driven demand.
Emerging Market Trends
Large-Format Porcelain Slab Adoption
Growing specification of large-format porcelain slabs, offering fewer grout lines and a more seamless aesthetic, is gaining traction in premium commercial lobby and retail applications, supported by advancing manufacturing technology enabling larger, thinner tile formats.
Recycled Content and Circular Economy Tile Products
Manufacturers are increasingly developing tile products incorporating recycled ceramic, glass, and post-industrial waste content, responding to intensifying building sustainability certification requirements and corporate environmental commitments among commercial building owners.
Antimicrobial and Hygienic Surface Technology
Growing demand for antimicrobial-treated tile surfaces in healthcare and hospitality applications continues to expand, reflecting heightened commercial building hygiene expectations that intensified following recent public health considerations.
Digital Design Visualization Tools for Specifiers
Manufacturers are increasingly offering digital visualization and augmented reality tools enabling architects and designers to preview tile installations within commercial space renderings before purchase, streamlining the specification process for large-scale commercial projects.
Key Companies in the Commercial Flooring Tiles Market
-
Mohawk Industries Inc.
-
RAK Ceramics PJSC
-
Grupo Lamosa S.A.B.
-
Kajaria Ceramics Limited
-
Iris Ceramica Group
-
Grupo Fragnani (Portobello)
-
Interface Inc.
-
Tarkett S.A.
-
Marazzi Group (Mohawk)
-
Somany Ceramics Limited
-
Other Regional and Specialized Tile Manufacturers
Report Target Audience
-
Tile and Flooring Manufacturers
-
Architects and Interior Design Firms
-
Investment and Private Equity Firms
-
Commercial Real Estate Developers and Owners
-
Building Materials Distributors and Retailers
-
Management Consulting and Advisory Firms
-
Green Building Certification Bodies
-
Academic Researchers in Construction Materials
Market Segmentation Summary
By Material Type
-
Porcelain/Vitrified Tiles
-
Ceramic Tiles
-
Luxury Vinyl Tiles (LVT)
By End-Use Sector
-
Offices
-
Retail
-
Hospitality
-
Healthcare
-
Education
By Application
-
New Construction
-
Renovation & Replacement
By Region
-
Asia Pacific
-
Europe
-
North America
-
Middle East & Africa
-
Latin America
About GMI Reports
GMI Reports is a leading market intelligence and research firm delivering actionable insights across a broad spectrum of industries globally. Our rigorous research methodologies, extensive primary and secondary data sources, and sector-specialist analysts enable our clients to make informed strategic decisions in complex and fast-evolving markets.
For further information, customized research, or licensing inquiries, please visit www.gmigreports.com or contact our research team directly.
www.gmigreports.com